
Understanding Home & Personal Loan EMI Calculations: A Complete Guide
Learn how Equated Monthly Installments (EMI) are calculated for home, car, and personal loans, with breakdown charts and repayment strategies.

Written by Aaradhya Pathak
Founder, Snab Innovations · Researched against official portal guidelines
Dimensions, file size rules, and accepted formats are verified against official portal notices. Tools on FileZenith process files directly inside your browser memory for complete privacy.
Use Tool Directly in Browser
Your files never leave your browser. 100% free, zero login required.
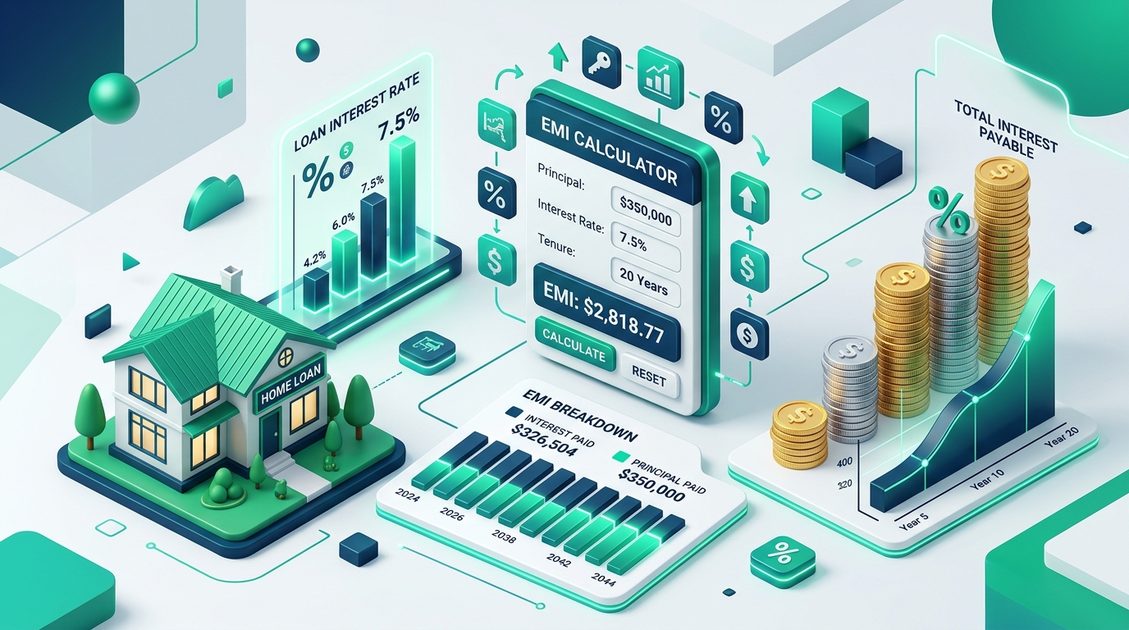
Planning a loan for a new home, car, or personal financial need requires understanding how your Equated Monthly Installment (EMI) is determined. Knowing the breakdown between principal repayment and interest charges helps you choose optimal loan tenures and save on interest.
How EMI Is Calculated: Formula Explained#
The standard mathematical formula for calculating EMI is:
EMI = [P x r x (1 + r)^n] / [(1 + r)^n - 1]
Where:
- P = Principal loan amount
- r = Monthly interest rate (Annual rate / 12 / 100)
- n = Loan tenure in total number of months
Understanding this interest amortization curve helps borrowers understand why early EMI installments go mostly toward interest payment.
3-Step Guide: Calculate Your Loan EMI Online#
Use FileZenith's financial tools to compute instant EMI repayment schedules:
Step 1: Input Loan Amount
Enter the principal loan amount you wish to borrow in our financial calculator suite.
Step 2: Set Interest Rate & Tenure
Adjust the slider or enter the annual interest rate offered by your bank along with the loan repayment duration in years or months.
Step 3: View Instant Amortization Breakdown
Instantly inspect your monthly EMI, total interest payable, and annual amortization payment schedule without submitting personal contact numbers or financial details.
Frequently Asked Questions (FAQ)#
Does increasing loan tenure reduce overall loan cost?
No. While a longer tenure reduces your monthly EMI amount, it significantly increases the total interest paid over the life of the loan.
Can pre-payments reduce total interest burden?
Yes! Making partial pre-payments early in your loan tenure directly reduces the outstanding principal, exponentially decreasing future interest accumulation.